Buying a home is an exciting milestone, but the process often comes with expenses that go beyond the property’s listed price. From inspections and appraisals to repairs and moving costs, unexpected bills can put pressure on your budget. Understanding these potential expenses early can help you make informed decisions and enjoy the homebuying journey with greater confidence.
1. Create a Realistic Homebuying Budget
Before beginning your property search, calculate how much you can comfortably afford. Your budget should include more than the down payment and monthly mortgage payments. Consider closing costs, property taxes, homeowners insurance, utility bills, and ongoing maintenance.
It is also wise to leave room for unexpected expenses. Even a property that appears well maintained may need repairs or upgrades after you move in.
Start by listing your expected costs and estimating a reasonable amount for each category. Research local prices, request quotes where possible, and avoid committing every available dollar to the purchase itself. A realistic budget provides flexibility when new expenses arise.
2. Prepare for Home Inspection and Appraisal Fees
A home inspection helps you understand the property’s condition before completing the purchase. An inspector may identify concerns involving the roof, plumbing, electrical systems, heating, cooling, or visible structural components. An appraisal, meanwhile, helps establish the property’s estimated market value for lending purposes.
These services have different purposes, and their fees may vary depending on the property’s location, size, age, and complexity. When researching the Average Cost Home Inspection US 2026, compare estimates from qualified professionals in your area rather than relying on a single national figure.
Ask what each service includes before booking. Some properties may also require specialized assessments, such as termite, sewer, radon, or foundation evaluations. These additional services can increase upfront expenses, but they may reveal issues that deserve attention before you finalize the purchase.
3. Set Aside Money for Closing Costs
Closing costs are among the expenses that surprise first-time buyers. These are the fees and prepaid items associated with finalizing a property transaction. Depending on the purchase, they may include lender charges, title services, recording fees, insurance, and prepaid property taxes.
The exact amount varies by location, mortgage type, and transaction details. Ask your lender for a loan estimate early in the process and review the closing disclosure before signing the final paperwork.
To prepare effectively:
- Request a written estimate of closing costs.
- Ask which charges are fixed and which may change.
- Review prepaid taxes and insurance requirements.
- Confirm the amount you must bring to closing.
- Keep some savings available for expenses after moving in.
Understanding these costs ahead of time can help you avoid last-minute financial stress.
4. Plan for Repairs and Maintenance
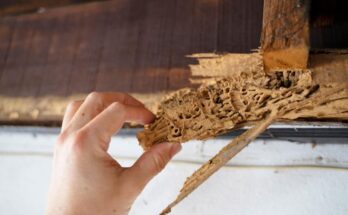
An inspection report may identify minor maintenance needs as well as more significant defects. Common examples include leaking faucets, damaged roof shingles, aging water heaters, worn flooring, and outdated electrical components.
Not every issue requires immediate attention. Separate the findings into three categories: urgent safety concerns, necessary repairs, and optional improvements. This makes it easier to prioritize spending after the purchase.
Before agreeing to buy the property, discuss significant findings with your real estate agent and, when appropriate, obtain estimates from licensed contractors. Depending on the contract and local rules, you may be able to negotiate repairs, request a credit, or reconsider the purchase.
Avoid assuming that every repair will be inexpensive. Keeping a contingency fund can help cover problems discovered during the first few months of ownership.
5. Account for Moving and Setup Expenses
Moving costs can quickly add up, particularly when you need professional movers, temporary accommodation, or storage. Even a short-distance move may involve packing supplies, transportation, cleaning, and time away from work.
Once you arrive, you may also need essential household items such as window coverings, light fixtures, tools, or appliances that are not included with the property.
Create a separate moving budget so these expenses do not interfere with your mortgage or emergency savings. Compare moving company quotes, check what each service includes, and plan ahead where possible. Buying essential items gradually rather than furnishing the entire home immediately can also make the transition more affordable.
6. Research Local Professionals and Services
Homebuying expenses can differ considerably between cities and neighborhoods. Local labor rates, property age, climate, and building practices may all influence the services a property needs.
For example, buyers researching home inspection los angeles can compare qualified local inspectors, review the scope of their services, and ask whether additional testing is recommended for a particular property. This approach helps buyers understand what they are paying for instead of choosing a service based on price alone.
Whenever possible, obtain written estimates and confirm whether follow-up visits or specialist evaluations cost extra. Ask questions if a quote is unclear, and verify professional qualifications before hiring someone. Comparing services carefully can help you avoid unnecessary charges while ensuring important concerns receive proper attention.
7. Build an Emergency Fund for Homeownership
Even after closing, homeownership brings ongoing financial responsibilities. Heating and cooling equipment can fail, plumbing problems can appear, and severe weather may create unexpected repair needs.
An emergency fund gives you more flexibility when these situations occur. Choose a savings target based on your income, essential monthly expenses, property condition, and insurance coverage. If saving a large amount immediately is difficult, begin with a manageable contribution and increase it over time.
Keep this money separate from your regular spending account so it remains available for genuine emergencies. Review your budget periodically as utility costs, insurance premiums, and maintenance needs change.
8. Review Every Expense Before Making a Decision
Unexpected costs are easier to manage when you understand your options. Read estimates carefully, ask for explanations of unfamiliar fees, and confirm important details in writing. If a contractor recommends extensive work, consider obtaining another qualified opinion before proceeding, particularly when the expense is substantial.
It is also helpful to distinguish between costs that are unavoidable and those that may be negotiable. Some expenses are required to complete the transaction, while others depend on the property’s condition, your preferences, or the terms of your agreement.
Most importantly, do not let the excitement of buying a home push you into spending more than you can reasonably afford. Taking time to review the numbers can protect both your budget and your long-term financial stability.
Conclusion
Managing unexpected homebuying expenses begins with realistic budgeting, careful inspections, and preparation for repairs and closing fees. Research local costs, compare professional estimates, and maintain emergency savings. With thoughtful planning and informed decisions, you can handle financial surprises more confidently and begin homeownership with greater peace of mind.